
Service Provider Fee Disclosures: What Sponsors Must Review Under 408(b)(2)
A 408(b)(2) fee disclosure is not a filing you archive. It is the document that lets a plan sponsor decide whether the fees the plan pays are reasonable for the services delivered.
Participant Data Feeds: Reconciling Payroll and Recordkeeper Records
Your payroll system and your recordkeeper should describe the same plan. When they don’t, the plan is being operated wrong. Here is the sponsor’s reconciliation procedure.
Beneficiary Designations: The 401(k) Records Sponsors Discover Too Late
Missing or stale 401(k) beneficiary designations surface at the worst possible moment. Here is the sponsor-side procedure for collecting, verifying, storing and auditing them.
Uncashed Distribution Checks: A Plan Sponsor’s Tracking and Escheatment Playbook
Uncashed distribution checks remain plan assets and remain a fiduciary responsibility. Here is how plan sponsors track, search, reissue and document them.
QDROs: What Plan Sponsors Must Do When a Domestic Relations Order Arrives
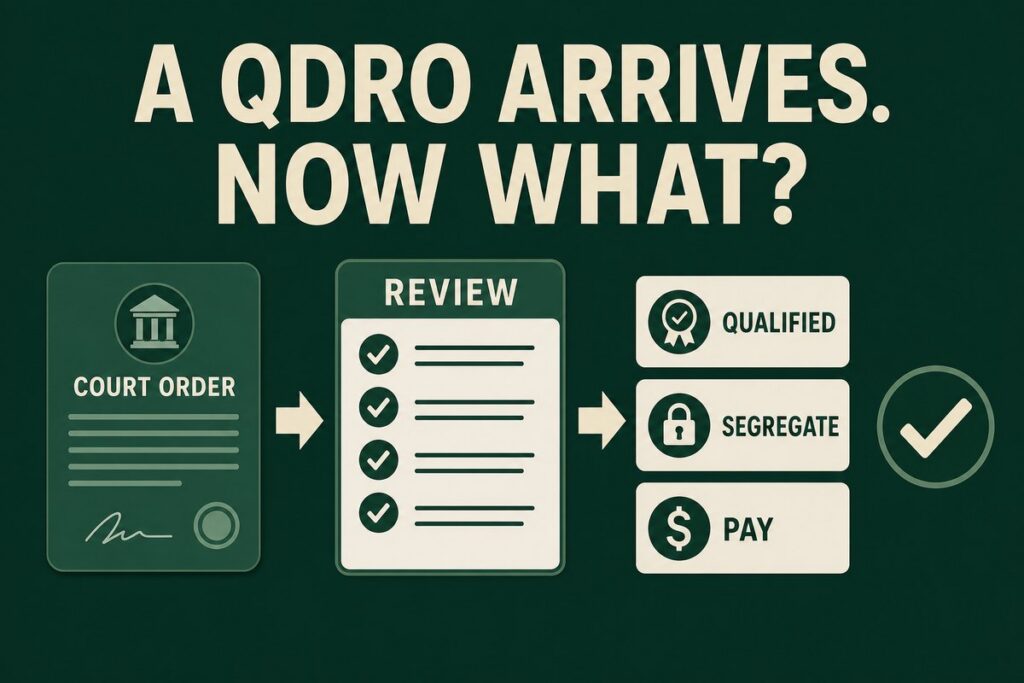
A domestic relations order is a fiduciary event, not a paperwork errand. Here is the sponsor’s review, segregation and payment procedure.
Plan Document Restatements: What Sponsors Sign and Why It Matters
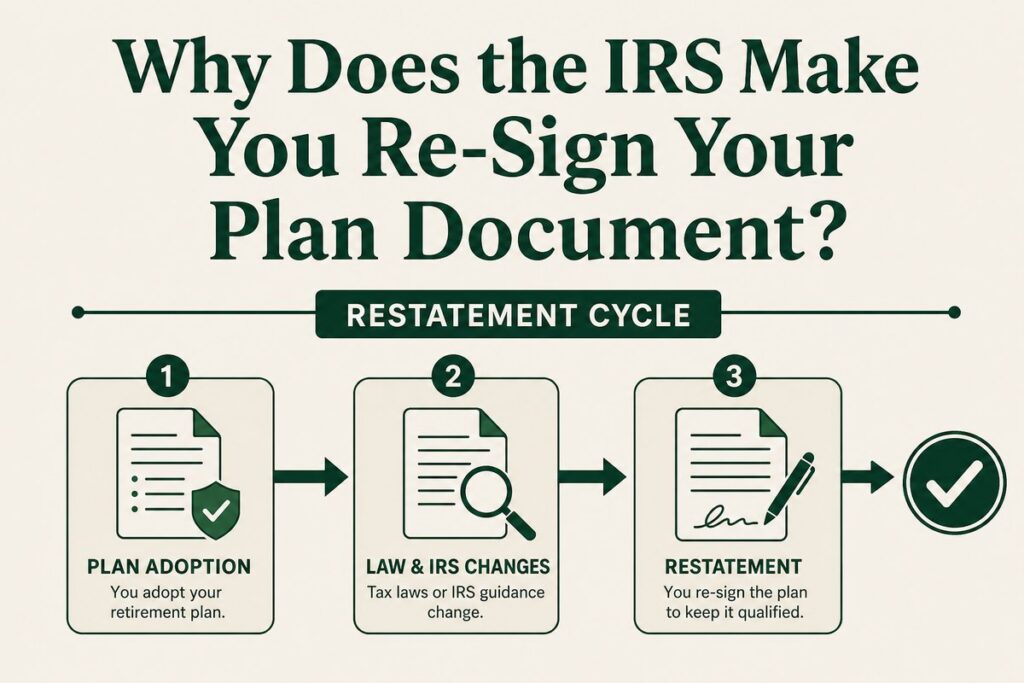
Restatement packets arrive looking like housekeeping. They are the legal terms of your 401(k) plan. Here is what plan sponsors should check before signing.
Plan Document vs. Operations vs. Notices: What Happens When Your 401(k) Records Disagree
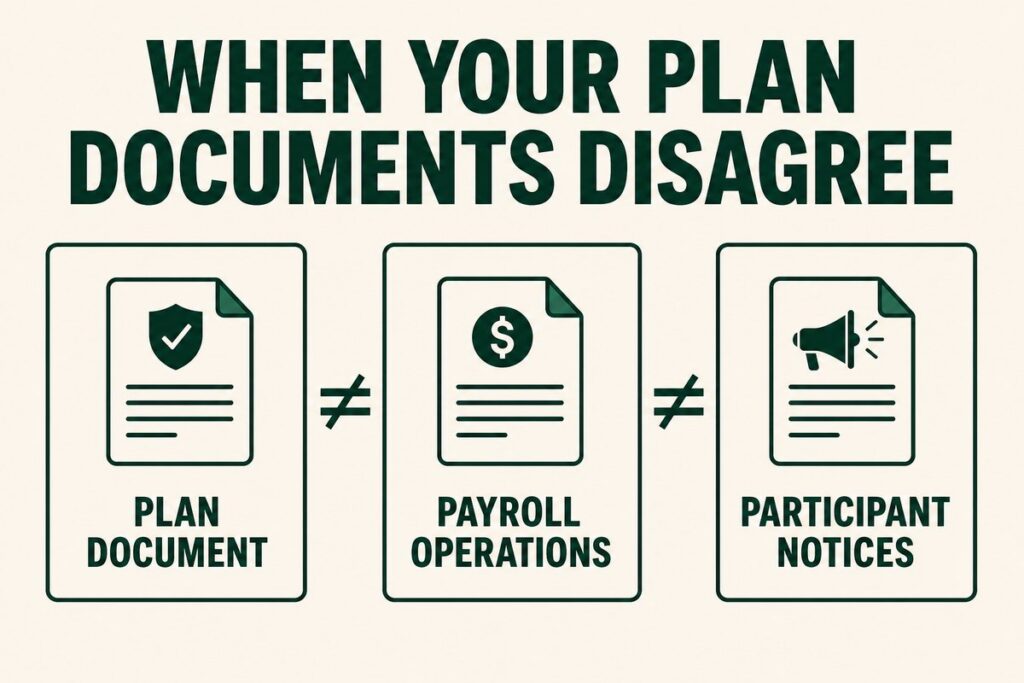
Most 401(k) audit findings trace back to one thing: the plan document, day-to-day operations and participant notices describing three different plans. Here is how plan sponsors reconcile them.
Forfeiture Accounts: How Sponsors Must Use Them and When
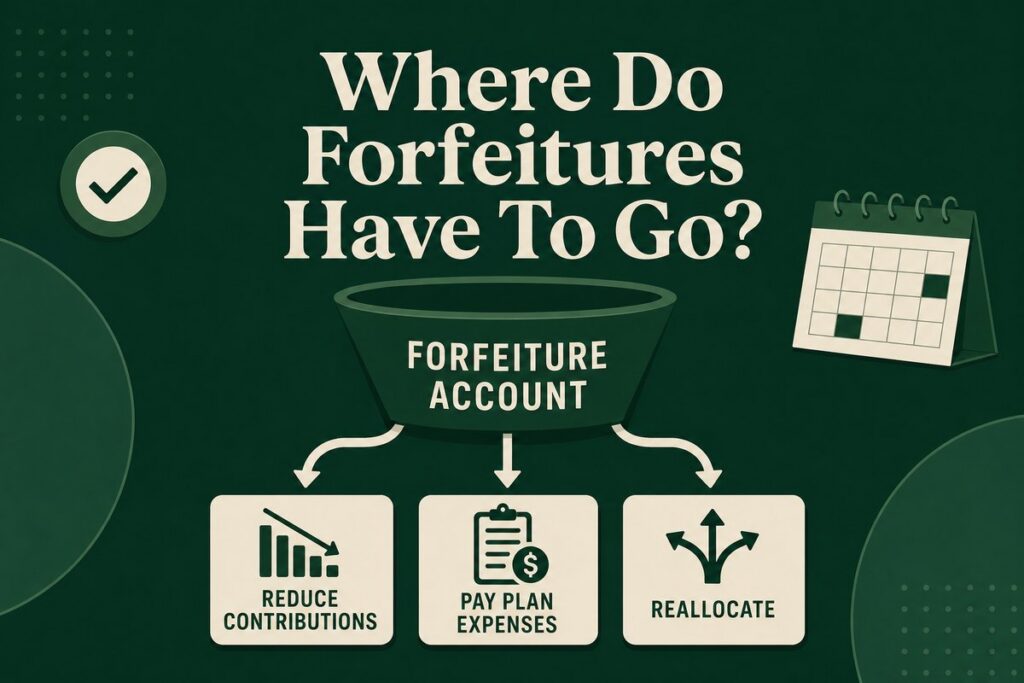
Forfeiture accounts are a fiduciary decision, not a parking lot. Here is how plan sponsors should use, time and document forfeitures under their plan document.
Missing Participants: What Sponsors Must Do Before Forfeiting or Distributing
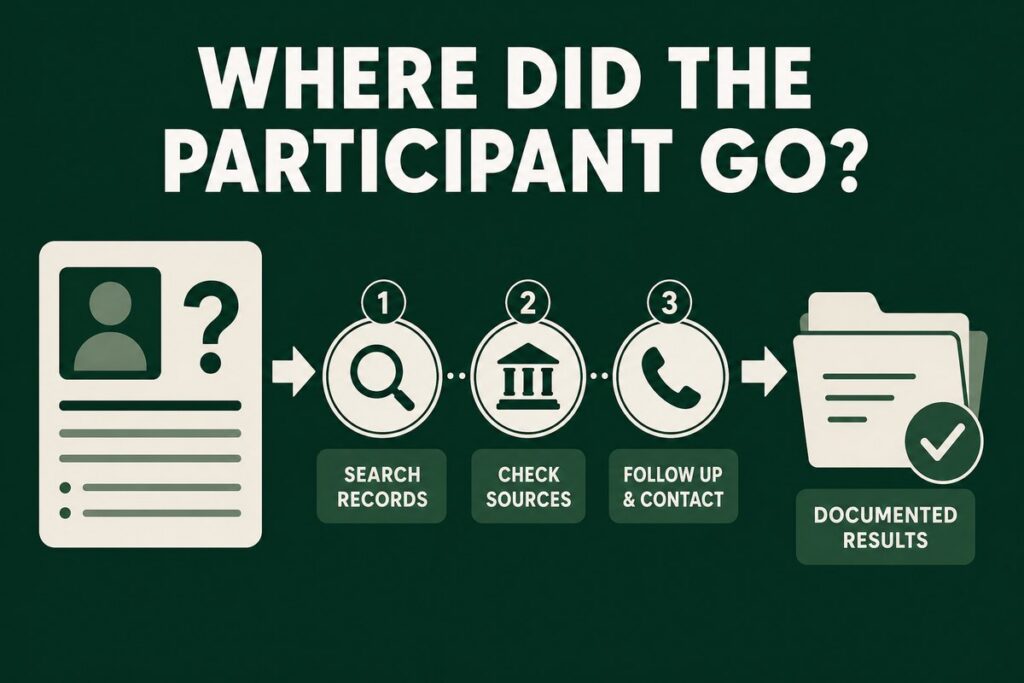
A missing participant is a fiduciary problem, not a mailroom problem. Here is the search, documentation and distribution path plan sponsors should follow before forfeiting or cashing out an account.
Controlled Groups and Affiliated Service Groups: When Another Entity Joins Your 401(k) Plan
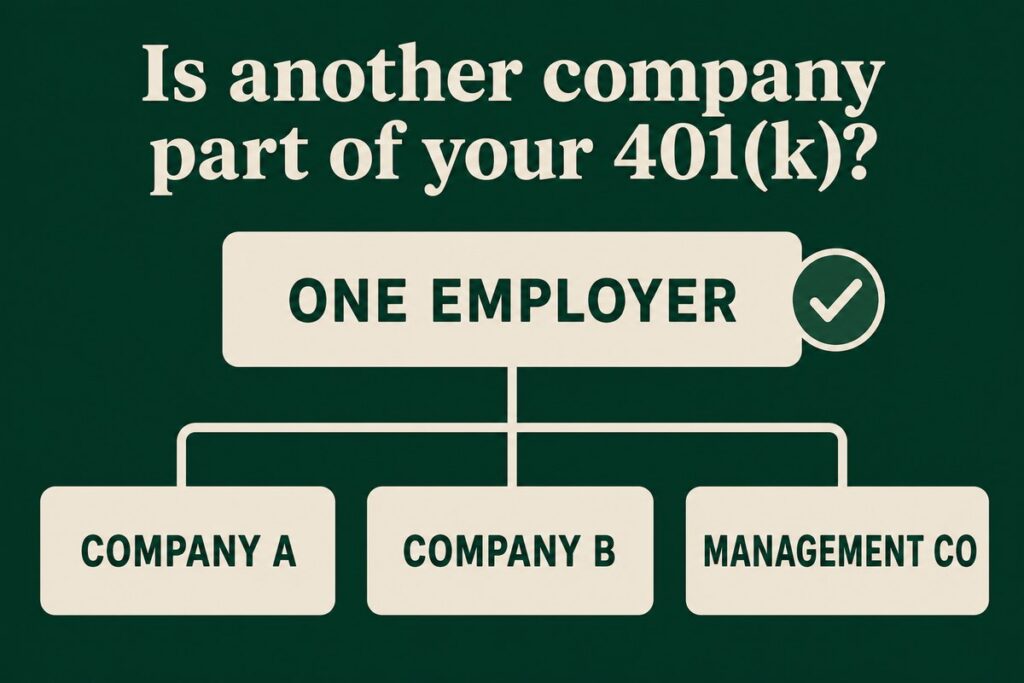
Controlled group and affiliated service group rules decide which employees must be counted in your 401(k) testing. Here is what plan sponsors must verify and document.
